Categories
Market UpdatesPublished October 27, 2026
Sell First or Buy First? A Move-Up Guide for Idaho Falls Homeowners (Contingent Offers, Builders & Timing)
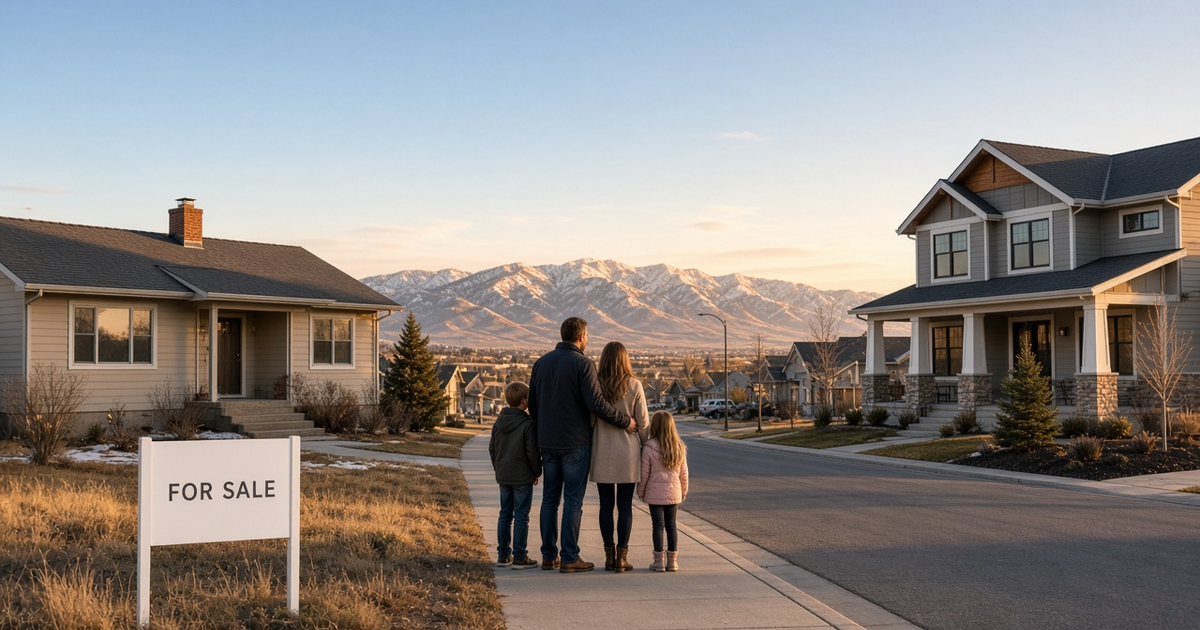
Short answer: for most Idaho Falls homeowners moving up this fall, I recommend selling first, or listing your home and writing a home-sale contingent offer on the next one at the same time. Buy first only if you can comfortably carry two housing payments for a few months, or you've lined up bridge financing with a lender. Bonneville County had 3.68 months of supply at the end of September 2026 and homes averaged 49 days on market in Q3 (Snake River MLS via Navica), so sellers are more open to contingent offers than they were a few years ago.
I'm Jacob Marcovitz, a REALTOR® with Keller Williams Realty East Idaho in Idaho Falls. A lot of the people I help are past clients and neighbors who've outgrown their first house, plus buyers who want a new build but have a home to sell first. This is the same walk-through I give them at the kitchen table: the three ways to do it, how contingent offers work on Idaho contracts, where new construction changes the timing, and a checklist you can follow.
Should I sell my house before buying another one in Idaho Falls?
Usually, yes, or at least list it before you write an offer. Selling first tells you exactly how much equity you have to work with and keeps you from carrying two mortgages. The trade-off is that you might have to move twice. Here's how the three paths compare.
Sell first, then buy
- Best for: homeowners who need their equity for the next down payment, or who can't qualify for two payments at once
- Upside: you know your exact sale price, and you write offers with no home-sale contingency, which makes them stronger
- Downside: you may need a rent-back, a short-term rental or a stay with family between homes
Buy first, then sell
- Best for: buyers with enough cash or income to carry both homes, or who've arranged bridge financing
- Upside: one move, and you can list your old home empty, cleaned and staged
- Downside: two payments, plus utilities, insurance and taxes on both, until the old home closes, and pressure to take a lower offer if it sits
Sell and buy at the same time (contingent offer)
- Best for: most move-up buyers in today's market, especially if your current home is under $500,000
- Upside: both closings can be lined up for the same day or within a few days of each other
- Downside: some sellers and builders won't accept a sale contingency, and two transactions linked together means a delay in one can hold up the other
How do I sell first without moving twice?
The cleanest tool is a rent-back, where you stay in the home for a set time after closing. On the standard Idaho REALTORS® purchase agreement (the RE-21), the possession line lets the parties choose keys "upon closing" or on a specific date, so a later move-out date can be negotiated into the deal. I put the terms in writing: how long you'll stay, what you'll pay per day, who covers utilities and what happens to a deposit if you leave damage or stay past the date. The buyer's lender may also limit how long a seller can stay after closing, especially when the buyer plans to live in the home, so we ask early.
Other ways to bridge the gap:
- Ask for a longer closing: setting closing further out gives you time to find and get under contract on the next house.
- Make your sale contingent on finding a home: some buyers will accept it, but it's a harder sell, and it can scare off buyers who need a firm date.
- Short-term housing: a furnished rental or extended-stay suite for a month or two. My temporary housing and first 90 days guide covers the options around Idaho Falls. It's written for INL relocators, but the same places work for local move-ups.
- Storage plus family: not glamorous, but it's the cheapest bridge, and it turns you into a buyer with no home to sell.
Can I buy first with a home-sale contingency in Idaho Falls?
Yes. A home-sale contingency says your purchase depends on your current home selling (or closing). The RE-21 has a yes/no box for exactly this: "This offer is contingent upon the sale, refinance, and/or closing of any other property." The details, like your home's address, whether it's already listed and the deadline for it to go under contract, go into the contract terms.
Sellers who accept a contingent offer often protect themselves with the Idaho REALTORS® RE-27, "Seller's Right to Continue to Market Property." According to the Idaho REALTORS® Legal Hotline, the RE-27 lets the seller keep accepting offers, and if a better one comes in, you have 72 hours (or whatever window the form specifies) to remove your contingency or lose the house. That's sometimes called a "kick-out" clause. Also know that by default, the RE-21 requires all contingencies to be satisfied or removed 7 calendar days before closing unless the contract sets a different number, so the timing on your sale matters.
How strong is a contingent offer right now? Stronger than in tight years, and it depends on price range. These are Bonneville County numbers at the end of September 2026, using the last six months of sales (Snake River MLS via Navica, residential, data through 10/3/2026, from my Fall 2026 market update):
If the home you're buying is under $500,000
- Months of supply: 3.16
- Average days on market (sold): 46
- What it means for a contingent offer: this band is still close to balanced. On a well-priced home, expect competition from buyers with no home to sell. Having your home already listed, or under contract, helps a lot.
If the home you're buying is $500,000 to $1 million
- Months of supply: 4.43
- Average days on market (sold): 59
- What it means for a contingent offer: this is where most move-ups land, and sellers have fewer buyers to choose from, so a contingent offer gets a real look, especially on homes that have been on the market a while.
Market-wide, Q3 2026
- Median sale price: $395,000 (Q3 2025: $400,000)
- Sale price vs. final list price: 98.6%
- New contracts: down about 12% from Q3 2025 (ESTIMATE, counted from list and pending dates in the MLS export)
- Source: Snake River MLS via Navica, residential, Bonneville County, data through 10/3/2026
My short version: in Idaho Falls this fall, a contingent offer is workable on most move-up homes if your house is priced right and ready to list. The weakest contingent offer is on a house that isn't even on the market yet. The strongest is "my home is already under contract and the inspection is done."
Should I use a bridge loan or HELOC to buy first?
They're both ways to tap your current home's equity before it sells, so you can make a non-contingent offer. Here's how they work in general. Rates, fees and whether you qualify depend on the lender and your finances, so talk to a lender before you count on either one.
Bridge loan
- What it is: a short-term loan secured by your current home, meant to be paid off when it sells
- Good fit: you have solid equity and expect your home to sell fairly quickly
- Ask the lender: the term, fees, whether payments are due monthly or at payoff, and how they count it when you qualify for the new mortgage
HELOC (home equity line of credit)
- What it is: a line of credit against your current home that you can draw on for the down payment
- Good fit: you plan ahead; ask the lender whether they'll still open one after your home is listed for sale
- Ask the lender: whether the rate is variable, any closing or early-payoff costs, and how the payment affects your debt-to-income ratio
Some lenders also have their own buy-before-you-sell programs. Whatever you use, get the new mortgage pre-approval in writing with the bridge payment counted, not just a verbal "you should be fine."
I'm buying new construction. When should I list my current home?
New construction is the easiest version of this problem, because the build gives you a runway. Production builders around Idaho Falls usually quote about six to nine months for a home that hasn't started, and custom builds run longer (see my production vs custom builder guide and Rockwell build timeline post for the builders' own numbers). That means you don't have to sell first or buy first. You can sign on the build, then list your home as the new one gets close.
- Don't list too early: build dates slip with weather, permits and materials. A good time to list is once the builder can give you a firm completion window. Then set your sale's closing a little after the builder's date, with a rent-back as a cushion.
- Ask about a home-sale contingency: some builders will consider one, especially on a home that hasn't started, and some won't. Every builder handles it differently, so ask before you pick a lot.
- Quick move-in homes work like resale: a finished or nearly finished spec home doesn't give you a runway, so the sell-first or contingent-offer rules above apply. My year-end new construction and quick move-in guide covers Q4 inventory.
- Watch the deposit: if your contract has a non-refundable earnest money or upgrade deposit and your home doesn't sell, that money can be at risk. Read the builder contract on this point before you sign.
- Broker compensation: some builders treat broker compensation as a buyer closing cost. Castlerock's pricing note does, for example (see my Castlerock guide). When that happens, I can negotiate to have my compensation covered as part of the offer, and I'll make sure you aren't overpaying.
What does a move-up timeline look like?
Here's the order I walk clients through. It works whether you sell first, buy first or do both at once.
- Talk to a lender first. Get pre-approved for the new home two ways: with your current home sold, and with it not sold. That tells you which paths are even on the table.
- Know your number. I'll pull comps for your home so you know your likely sale price and net equity, not just a website estimate.
- Pick your path. Sell first, buy first or contingent, based on your equity, your payment comfort and how much risk you're OK with.
- Get the house ready. Do repairs, declutter and pre-pack before you list. Q3 homes averaged 49 days on market (Snake River MLS via Navica, Bonneville County), so plan for about seven weeks, with the first two weeks mattering most.
- Shop with your timeline in mind. Tour homes before you list so you know what's out there, then write when your home is listed or under contract.
- Line up the dates. Match closing dates, add a rent-back if needed and book movers early. Spring and summer are busier, and my seasonal timing guide shows how Bonneville County sales shift through the year.
- Close and move. Do your final walkthrough, hand over keys and change your address.
Will I owe taxes when I sell my current home?
Often not on the gain, if it's been your main home. Per the IRS (Topic 701), you may be able to exclude up to $250,000 of gain from the sale of your main home, or up to $500,000 if you file a joint return with your spouse, if you owned and lived in the home for at least two of the five years before the sale. There's more detail in IRS Publication 523.
That matters if you're tempted to buy first and keep your old house as a rental. The two-out-of-five-year test keeps running after you move out, so renting it for a while can affect the exclusion when you eventually sell. I'm not a tax advisor, so talk to a CPA before you decide to keep it.
Is fall or winter a bad time to make a move-up?
Not in Idaho Falls this year. There are fewer buyers in fall and winter, but more inventory gives you more choices on the buy side, and the buyers who are out are usually serious. If you can wait, listing in spring gives you the most buyers, but you'll also be buying in a busier market. My fall and winter timing guide and what winter is really like cover the trade-offs.
More guides for move-up buyers and sellers
- Market numbers: Eastern Idaho real estate market update: Fall 2026
- Where to move up to: Idaho Falls neighborhood guide and Idaho Falls vs. Ammon
- New construction: every local builder on my new construction page, plus my production vs custom guide
- Costs: Idaho Falls cost of living and property taxes and HOAs explained
- Relocating for INL: INL relocation guide and out-of-state relocator buying guide
- About me: Meet Jacob Marcovitz, Realtor at Keller Williams East Idaho
Market figures come from Snake River MLS data (via Navica) for residential property in Bonneville County, data through October 3, 2026, as published in my Fall 2026 market update; counts labeled ESTIMATE are derived from list and pending dates. Contract details are from the Idaho REALTORS® RE-21 (March 2026 edition) and the Idaho REALTORS® Legal Hotline. Every transaction is different, and nothing here is legal, tax or lending advice. Talk to a lender, a CPA or an attorney for your situation.
Jacob Marcovitz, REALTOR®, Keller Williams Realty East Idaho, 3525 Merlin Dr, Idaho Falls, ID 83404. Thinking about a move-up? Call or text 208-821-6217, or connect with me here, and I'll pull the comps for your home.
Jacob Marcovitz
| Jacob Marcovitz | Keller Williams Realty East Idaho
or another way